ISM Manufacturing PMI — August 2026
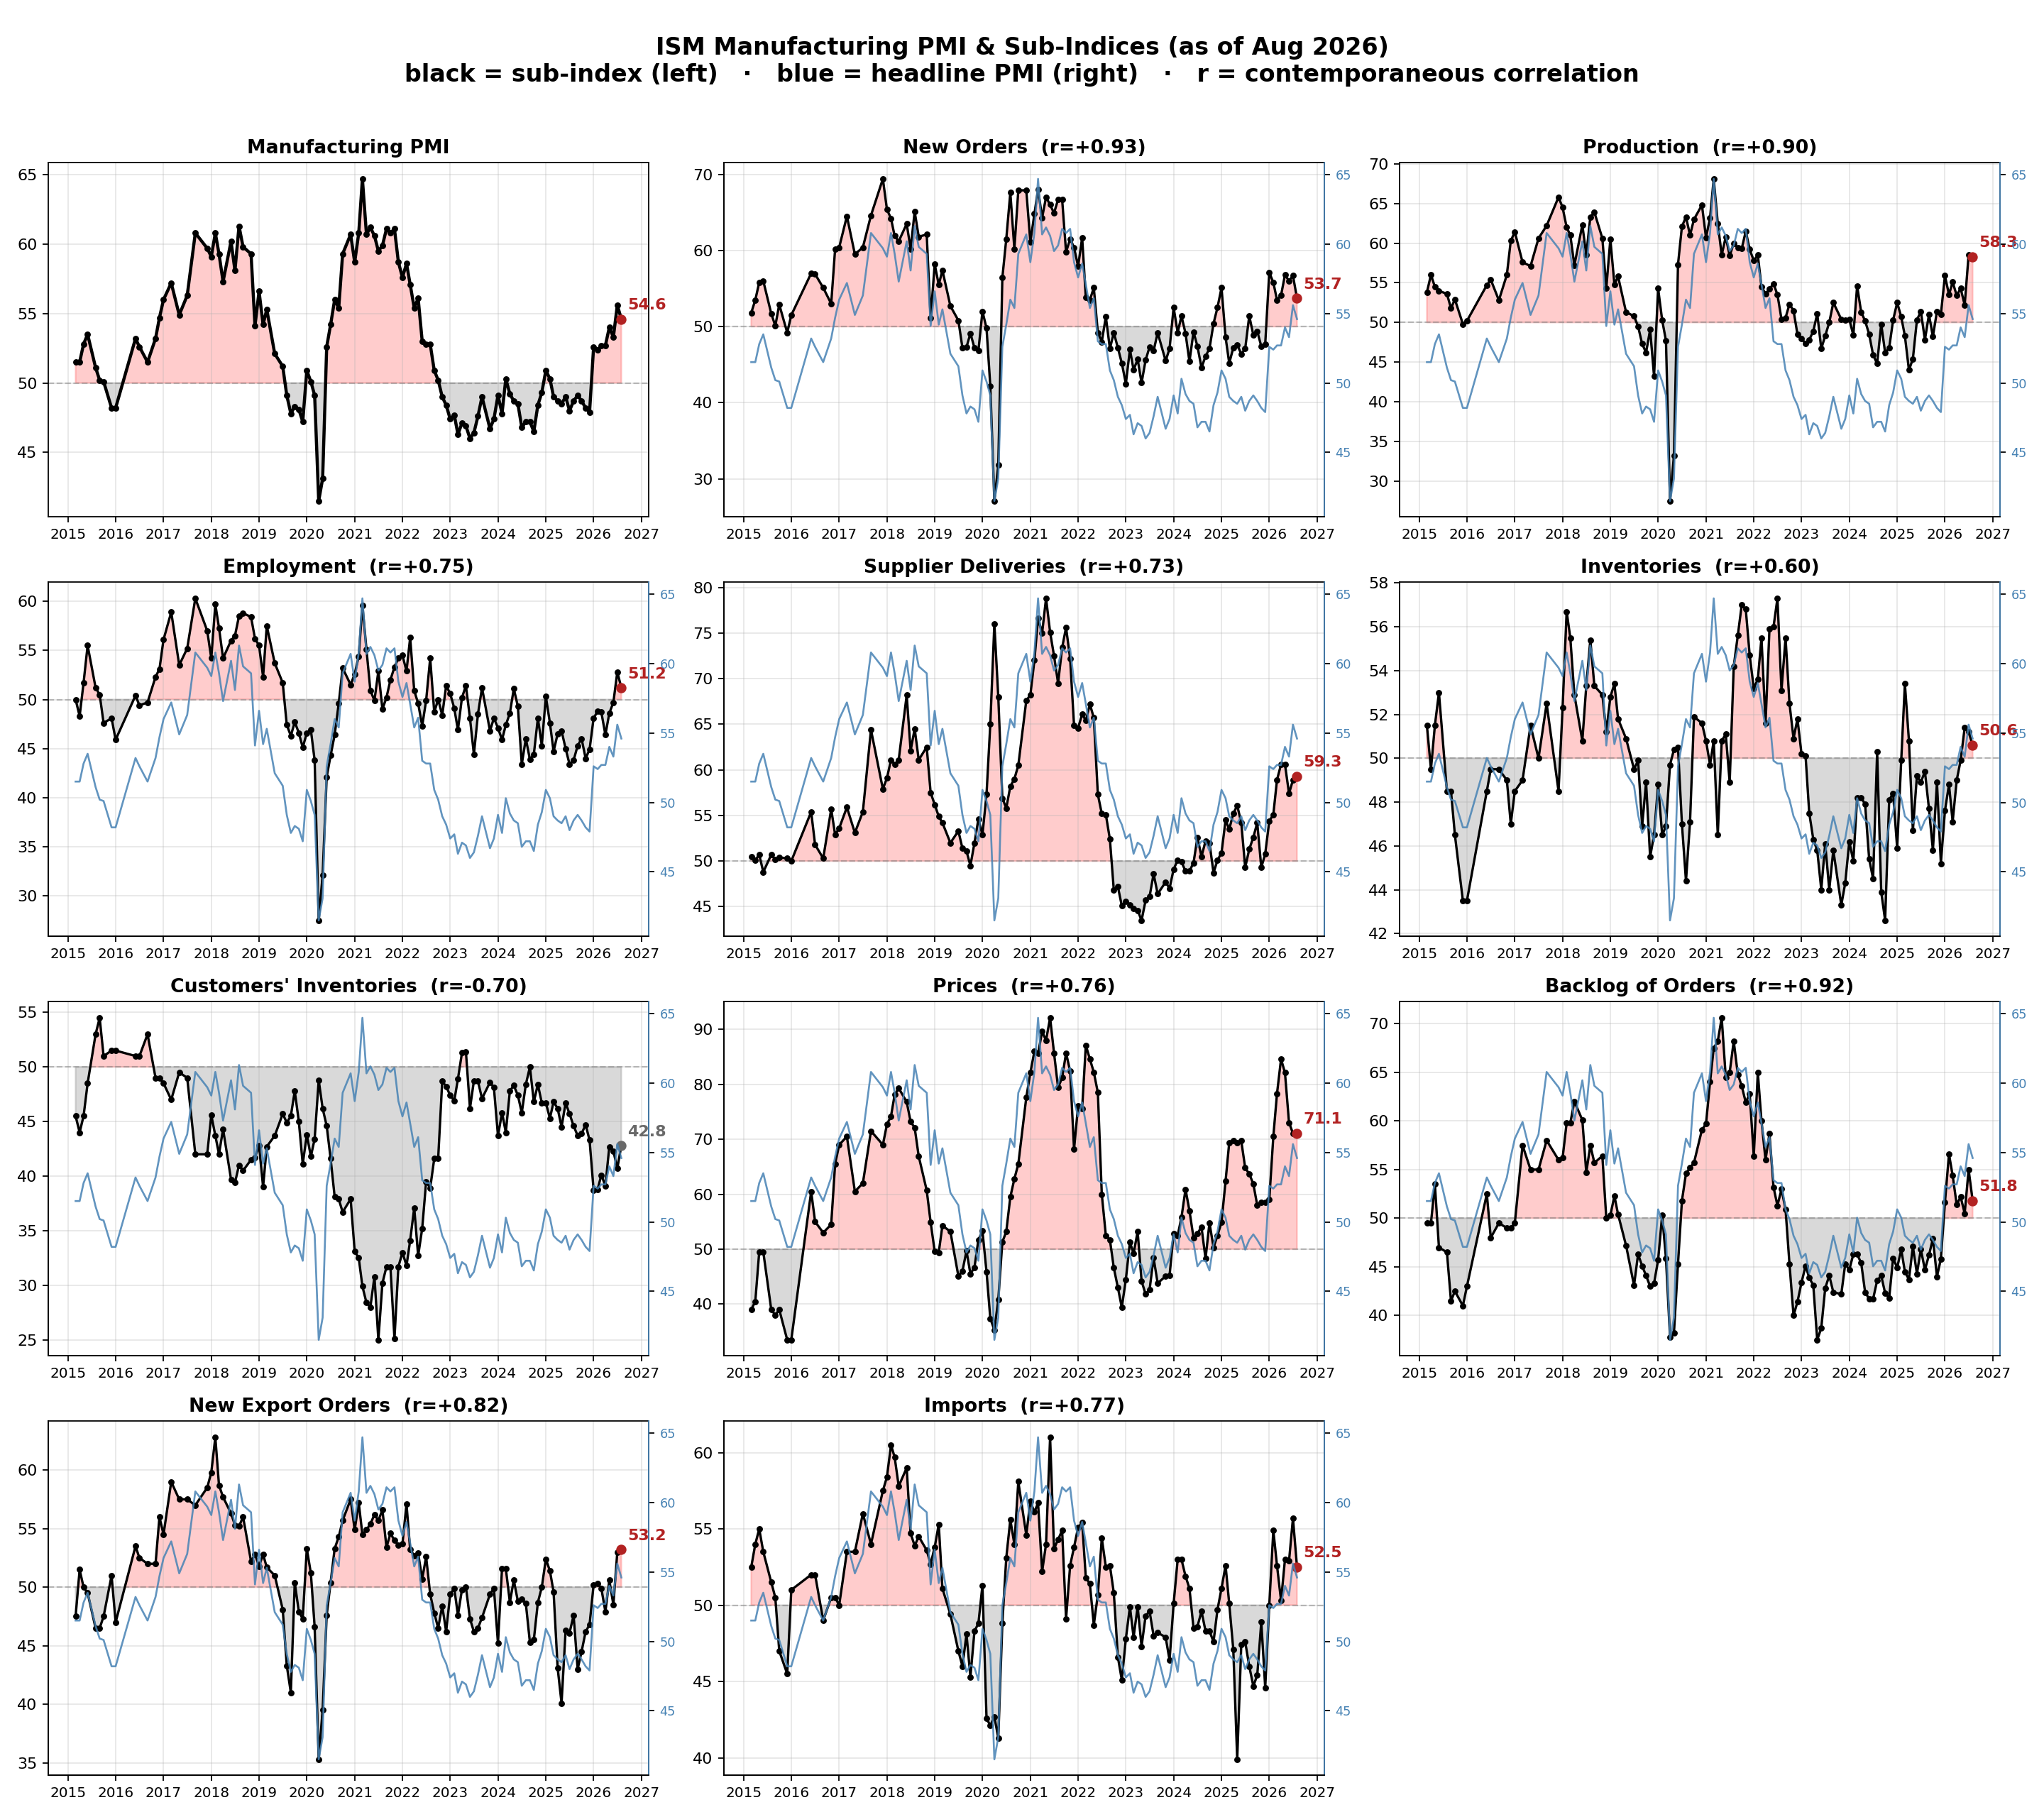
Headline: The PMI fell 1.0 point to 54.6, but manufacturing continued to expand for an eighth consecutive month, at a slower rate. The reading was above the trailing six-month average of 53.4 and remained within the 52.4–55.6 six-month range. It also indicates a growing broader economy, comfortably above the 47.5 breakeven level.
Sub-indices:
| Index | Level | Prior | Change | Direction | vs 6-mo |
|---|---|---|---|---|---|
| New Orders | 53.7 | 56.7 | -3.0 | Growing | above avg (55.5) |
| Production | 58.3 | 58.5 | -0.2 | Growing | above avg (54.5) |
| Employment | 51.2 | 52.8 | -1.6 | Growing | above avg (49.2) |
| Supplier Deliveries | 59.3 | 58.9 | +0.4 | Slowing | above avg (58.6) |
| Inventories | 50.6 | 51.2 | -0.6 | Growing | above avg (49.6) |
| Customers' Inventories | 42.8 | 40.7 | +2.1 | Too Low | 6-mo high |
| Prices | 71.1 | 71.1 | 0.0 | Increasing | below avg (76.6) |
| Backlog of Orders | 51.8 | 55.0 | -3.2 | Growing | below avg (53.4) |
| New Export Orders | 53.2 | 53.0 | +0.2 | Growing | 6-mo high |
| Imports | 52.5 | 55.7 | -3.2 | Growing | below avg (53.2) |
Key moves:
- Customers’ Inventories rose to 42.8, a six-month high, but remained well below 50, indicating inventories at customers are still too low.
- New Export Orders reached a six-month high of 53.2, while New Orders fell to 53.7, below its six-month average of 55.5.
- Backlog of Orders declined 3.2 points to 51.8, below its six-month average, while Prices held at 71.1, below the six-month average of 76.6.
Insights:
- Current production remains a clear support at 58.3, well above its six-month average, but the forward demand profile softened: New Orders fell to 53.7 and Backlog to 51.8. This points to continued expansion with less momentum behind future output.
- The 50.6 Inventories reading is only marginally expansionary. With New Orders and Backlogs weakening, the modest inventory level is more consistent with caution around demand than deliberate stocking for a stronger order pipeline.
- Customers’ Inventories remain “Too Low” at 42.8, a bullish reorder signal despite the monthly increase. This provides some offset to the softer domestic order and backlog readings.
- Supplier Deliveries at 59.3 indicate slower deliveries and are above their six-month average, consistent with ongoing demand or supply-chain tightness rather than broad manufacturing slack.
- Prices remained elevated at 71.1 for a 23rd month, sustaining input-cost pressure. Although below the recent six-month average, the level remains a material margin and goods-inflation risk.
Breadth & prices: All 15 industries reported growth and none reported contraction. Input prices continued increasing, with the Prices Index unchanged at 71.1.
Takeaway: August confirms an expanding manufacturing cycle, with production and export demand resilient but domestic orders and backlogs losing momentum. Low customer inventories and continued delivery constraints support near-term activity, while elevated prices and a softer forward-order profile argue for slower growth with persistent margin pressure.