Market Briefing
Fav
Daily Pulse
Weekly Pulse
IBKR
Sentiment
Misc
Daily Market Pulse November 16, 2026
THOUGHT OF THE DAY
U.S. Closes China’s Cloud-Chip Access Loophole
Commerce closed the specific third-country leasing workaround that let Chinese entities access Nvidia computing power—an escalation beyond broader scrutiny of chip exports. The move adds regulatory risk to an already pressured chip sector as Nvidia faces a leadership crisis.
Signal: Keep exposure to China-sensitive AI hardware measured; watch for details on enforcement and any effect on demand ahead of Nvidia’s earnings call.
PepsiCo Cuts 2026 Core EPS Growth Guidance
PepsiCo cut its 2026 core EPS growth outlook to 2.5%–3.5% from 5%–7%, citing weaker North American volumes and margin pressure. The reduction marks a clear deterioration in the outlook, not just a continuation of the company’s existing cost challenges.
Signal: Treat the guidance cut as a warning on consumer-staples volume and pricing power; look for confirmation in upcoming retailer results.
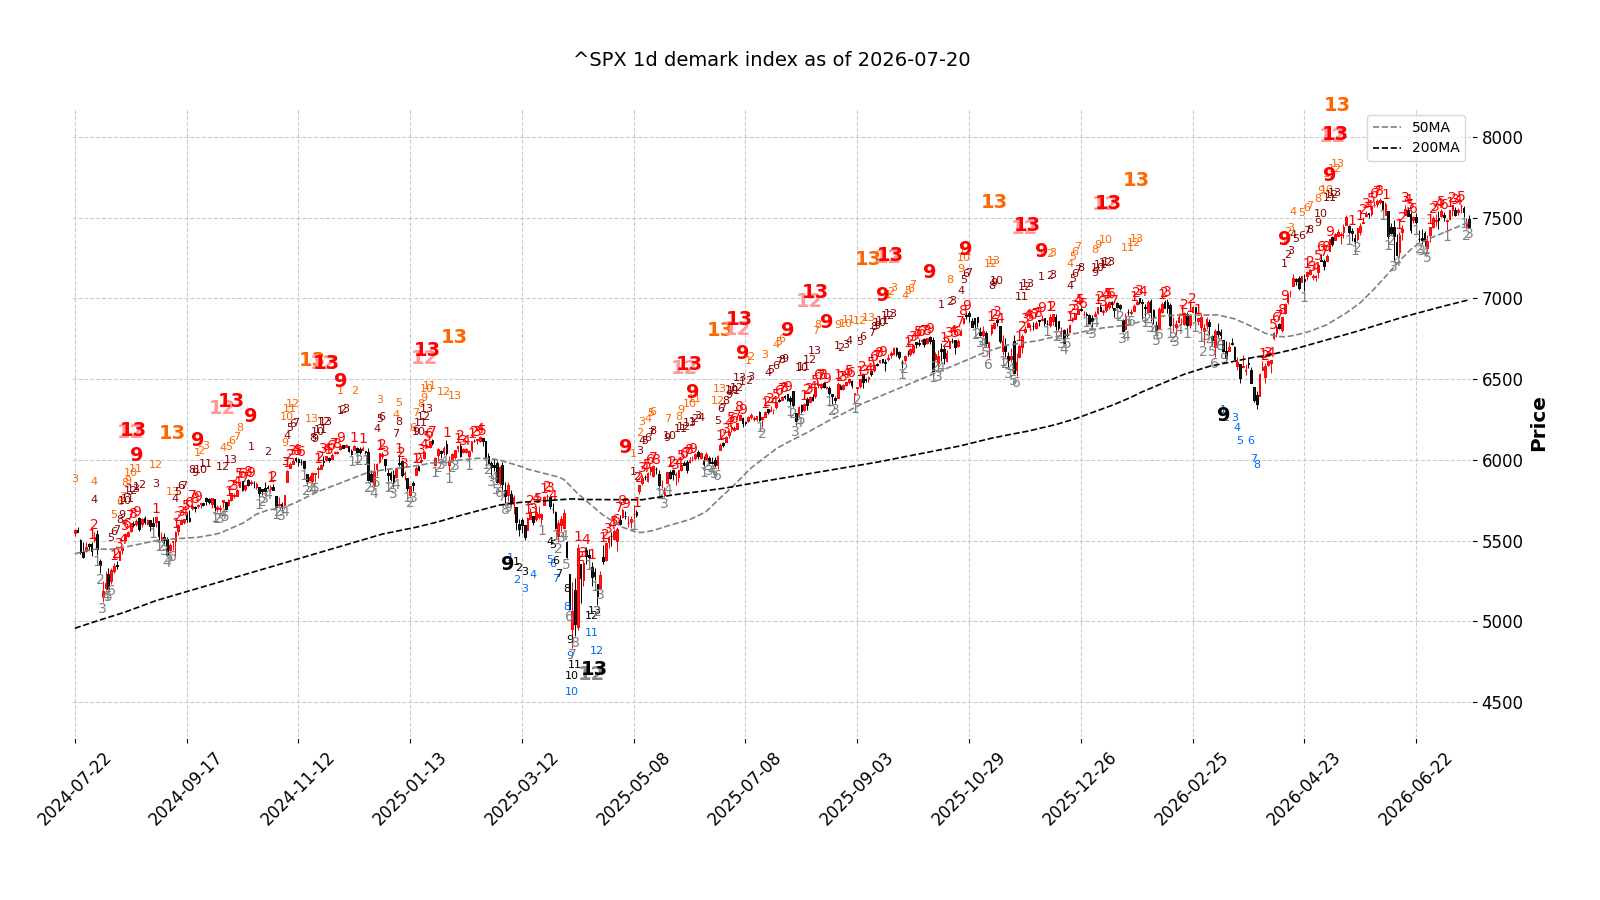
MACRO SUMMARY
Today’s Read: Markets priced a sharper risk premium into technology after the Commerce Department shut the China chip-access workaround, adding to concerns around Nvidia’s leadership crisis. The Nasdaq 100 fell 2.3%, volatility protection drew demand, and defensive sectors led; Treasury yields and the dollar were nearly flat amid a light U.S. data calendar. The contrast in corporate signals is stark: PepsiCo’s weaker North American volumes and margin pressure point to strain in parts of the consumer economy, while AI infrastructure demand remains strong but increasingly exposed to policy and financing risks.
Oil fell 3% as Middle East exports strengthened and geopolitical tensions cooled. A larger energy supply outlook could ease inflation pressure: if WTI stabilizes in the $70s, it may support the possibility of rate cuts in summer 2027, alongside lower fuel costs for consumers and businesses. But the policy shift that triggered today’s chip selloff, together with lender caution toward AI infrastructure projects, shows that lower energy costs do not remove the near-term risks to tech investment and credit availability.
Forward Catalysts
- Nvidia’s earnings call on November 17: Watch for updates on leadership, regulatory exposure, and AI spending.
- Retail earnings this week: Results and guidance from Home Depot, Lowe’s, Target, Walmart, and TJX will provide a read on consumer resilience; Lowe’s and Target report November 18, and Ross Stores reports November 19.
ACTIONABLE IDEAS
Actionable Ideas (Negative)
- PEP(PepsiCo): The company cut 2026 core EPS growth guidance to 2.5%–3.5% from 5%–7% as North American volumes weakened and margins tightened. Avoid adding ahead of evidence of volume stabilization or a credible margin recovery.
- NVDA(NVIDIA): The closure of the third-country leasing workaround raises China-access risk as the company heads into its November 17 earnings call amid a leadership crisis. Keep positioning defensive until management clarifies the regulatory and leadership implications.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 15, 2026
THOUGHT OF THE DAY
Inflation Reignites Higher-for-Longer Rate Bets
Hotter inflation readings and hawkish Fed commentary have pushed Treasury yields above 5% and brought further rate hikes back into market discussion, extending the repricing beyond elevated odds of a December increase. That raises the discount rate for long-duration assets and increases financing pressure on borrowers.
Signal: Favor balance-sheet strength and near-term cash generation; treat highly valued, long-duration assets as exposed while yields remain above 5%.
Oil Market Swings Toward Structural Oversupply
The IEA’s forecast of a Q4 surplus, alongside a projected 3.3 million barrel-per-day supply increase and 420 million barrels of emergency stock releases, marks a sharp break from tight-market expectations. Geopolitical risks still threaten supply, but the outlook now pairs that risk premium with weaker demand and a much larger supply cushion.
Signal: The balance of risk has shifted against crude; watch Gulf exports, inventory builds, and stock-release plans for confirmation before adding oil exposure.
MACRO SUMMARY
Today’s Read: Inflation is again driving the macro narrative. The summaries cite producer-price inflation of 6.5% year over year, core PPI of 5%, and a Fed-preferred inflation measure at 3.6%. With the 10-year Treasury yield above 5% and Fed officials signaling little urgency to ease, markets face a higher-for-longer rate path, raising financing costs and weighing on valuations for growth stocks and other long-duration assets.
Company signals point to an uneven economy rather than a broad demand collapse. Discretionary home-project intentions fell from 49% to 37%, while retail earnings are approaching as a test of household resilience. At the same time, producer-cost pressure threatens consumer-goods margins where companies cannot pass through higher inputs. Tighter credit also raises the bar for leveraged borrowers and capital-intensive projects, even as firms with strong cash generation or recurring revenue remain better positioned.
Oil adds a significant countercurrent: the IEA’s surplus forecast and emergency stock releases weaken the supply-demand case for crude, while Middle East tensions could still disrupt flows and renew price pressure. The macro tension is clear: disinflation is not assured, but oil supply may expand sharply. That combination complicates the inflation outlook and leaves rate-sensitive assets vulnerable to renewed volatility.
Forward Catalysts
- Fed decision in December: Markets will assess whether persistent inflation and hawkish commentary translate into another rate increase.
- Upcoming U.S. housing construction and sales data: The releases could test whether housing remains resilient enough to reinforce the case for restrictive policy.
- Retail earnings this week: Results from Walmart, Target, TJX, Lowe’s, and Ross Stores will offer evidence on consumer demand, pricing power, and margins.
- Upcoming earnings from Alibaba, PDD, and Palo Alto Networks: Guidance will provide additional signals on China consumer demand and enterprise security spending.
ACTIONABLE IDEAS
Actionable Ideas (Positive)
- SMFG(Sumitomo Mitsui Financial Group): Raised its annual profit forecast to a record on stronger lending income. Use the results as support for selective Japanese-bank exposure, while monitoring whether higher rates continue to lift margins without worsening credit quality.
Actionable Ideas (Negative)
- USO.US(United States Oil Fund): The IEA’s projected Q4 surplus, expected supply growth, and the 420 million-barrel emergency release weaken the crude outlook; a U.S. inventory build adds confirmation. Favor a tactical underweight or short position, with a clear risk limit for a renewed Middle East supply shock.
- SMMT(Summit Therapeutics): The FDA rejected ivonescimab’s application after the trial failed to show the required overall-survival benefit, and the company has not outlined a resubmission timeline. Avoid the stock pending a credible regulatory and clinical path forward.
- MSTR(MicroStrategy): Bitcoin’s decline left the company’s holdings with a reported $9.36 billion unrealized loss, while U.S. spot Bitcoin ETFs saw nearly $3 billion in outflows. Higher yields raise the opportunity cost of holding crypto and compound the risk in MSTR’s leveraged, Bitcoin-linked equity. Underweight or avoid until outflows stabilize and Bitcoin regains durable support.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 14, 2026
THOUGHT OF THE DAY
FAA Router Failure Grounds Nationwide Air Travel
A faulty router upgrade at an FAA facility triggered a nationwide ground stop, disrupting more than 1.5 million passengers and leading to thousands of cancellations and delays. The escalation today is the Transportation Secretary’s $50 billion emergency funding request to modernize air traffic control, which turns a technical failure into a national infrastructure and policy issue. L3Harris (LHX)(L3Harris Technologies), whose work is under scrutiny, faces reputational and contract risk; American Airlines (AAL)(American Airlines), Delta Air Lines (DAL)(Delta Air Lines), United Airlines (UAL)(United Airlines), and Southwest Airlines (LUV)(Southwest Airlines) face recovery costs and renewed exposure to failures outside their control.
Signal: Treat airlines as exposed to an infrastructure shock, not as the cause; watch the LHX investigation and whether Congress advances the modernization funding request.
Hawkish Repricing Reaches the 10-Year Treasury
Today’s breakout is the spread of rate pressure from shorter maturities into the long end: the 10-year Treasury yield rose 30 basis points over the week, even as equity volatility revived demand for safety. That challenges Treasuries’ traditional role as an equity hedge and raises the discount-rate hurdle for long-duration assets. The reported 98% probability of a December Fed hike reinforces the risk that higher yields could persist rather than quickly reverse.
Signal: Reduce reliance on duration as a portfolio hedge; prioritize balance-sheet resilience and scrutinize leveraged, long-dated growth investments.
MACRO SUMMARY
Today’s Read: Corporate news points to a mixed economy under tighter financial conditions. Demand remains strong in selected investment areas: Applied Materials (AMAT)(Applied Materials) reported a 53% year-over-year revenue increase and issued guidance above expectations, while storage suppliers reported sharp gains tied to AI workloads. But the investment cycle is not risk-free: UBS estimates that nearly 30% of projected U.S. data-center capacity through 2028 could be delayed or paused, and capital-intensive operators face higher financing costs.
Inflation and rates remain the dominant macro constraint. The news flow cites October CPI up 0.4% month over month, core CPI at 0.3% for a third consecutive month, and core PCE at 3.1%. Together with the 10-year yield’s 30-basis-point weekly rise and near-certain market pricing of a December Fed hike, those readings point to tighter financial conditions and increased pressure on rate-sensitive valuations and borrowers. The Bank of England has also raised its policy rate to 4%; its chief economist has warned inflation could reach 5% by mid-2027, with markets pricing roughly 90 basis points of further tightening by the end of 2027.
Corporate signals on consumers and costs remain uneven. Dollar General’s account of shoppers trading down suggests value-focused retailers can capture demand, while airline disruption adds near-term operating and customer-recovery costs across the sector. Oil’s reported 17% decline in Brent since late October offers some relief to fuel-sensitive businesses, but the reported record in home-heating oil prices shows that household energy costs remain a pressure point. The macro risk is that persistent inflation and rising yields tighten credit before demand has clearly weakened.
Forward Catalysts:
- The Federal Reserve’s December policy decision, with markets assigning a 98% probability to a rate hike.
- The Bank of England’s next policy decisions as markets price roughly 90 basis points of additional tightening through 2027.
- Congressional action on the $50 billion FAA modernization funding request, alongside findings from the investigation into the router failure.
- Upcoming company reports explicitly flagged in the news flow: Baidu (BIDU)(Baidu) and Tyson Foods (TSN)(Tyson Foods) on November 16; Klarna (KLAR)(Klarna) on November 17; Alibaba (BABA)(Alibaba) on November 18; and Ciena (CIEN)(Ciena) on December 10.
ACTIONABLE IDEAS
Actionable Ideas (Positive)
- AMAT (Applied Materials): Q4 FY2026 revenue rose 53% year over year to $10.41 billion, EPS beat estimates, and Q1 guidance exceeded expectations. Use the raised outlook as confirmation of semiconductor-equipment demand, while sizing against higher-rate and sector-volatility risk.
- FERG (Ferguson Enterprises): Revenue and EPS beat expectations, organic sales grew 7%, and management raised its 2026 net-sales outlook to about 7% growth while tightening its margin range. The combination of growth and margin discipline supports a quality-growth position.
- NU (Nu Holdings): Quarterly net income rose 39%, revenue increased 45%, and the company added 3.7 million customers. Favor demonstrated customer growth and profitability over speculative growth narratives, while monitoring credit performance.
Actionable Ideas (Negative)
- AADX (Applied Aerospace & Defense): Management cut 2026 sales guidance because of program delays and rising costs. Avoid treating the low sales multiple as a value signal until execution and contract conversion improve.
- HIMS (Hims & Hers Health): The company swung to a $33 million net loss despite revenue of $890.4 million, with margins deteriorating amid regulatory and competitive pressure in weight-loss drugs. Avoid the turnaround thesis until profitability stabilizes and the business demonstrates more durable margins.
- NFLX (Netflix): Management reduced its 2026 advertising-revenue and free-cash-flow outlook after delays in ad features and partner integration. Stay underweight until execution validates advertising as a dependable growth and cash-flow driver.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 13, 2026
THOUGHT OF THE DAY
Nvidia Shock Reprices Semiconductor Risk
Today’s chip-flow scrutiny tied to China escalated the existing Nvidia governance shock into a broader export-control and AI-growth risk, while a sharp semiconductor selloff showed that investors are reassessing the sector beyond Nvidia itself. The concern now extends to the durability of Nvidia-led AI demand, including whether vendor financing and customer spending can sustain the buildout.
Signal: Treat semiconductor exposure as event-driven until Nvidia’s earnings clarify demand, China exposure and financing risks.
Microsoft Outage Exposes Cloud Reliability Risk
A global outage disrupted Outlook, Teams and Copilot for hours, turning cloud concentration into an immediate operational-resilience issue for enterprises. The disruption hit Microsoft’s core productivity tools and its flagship AI assistant, putting reliability—not just AI capability—under investor scrutiny.
Signal: Watch for evidence of stronger redundancy and customer impact; avoid treating a single outage as proof of lasting demand damage.
Corteva Cuts Guidance After Brazil Collapse
Corteva’s Brazil-driven sales slump and full-year profit cut exposed weak demand and excess inventory; the delayed SEC filing adds a new disclosure and execution concern beyond the previously reported guidance cut. The delayed filing raises the stakes as investors assess whether management can restore inventory discipline and reporting confidence.
Signal: Keep exposure defensive until Corteva files and shows Brazil inventory and demand stabilizing.
MACRO SUMMARY
Today’s Read: Corporate news points to uneven demand: Corteva’s Brazil business weakened sharply, while the semiconductor selloff reflects investors questioning whether AI demand and financing can support current growth expectations. Microsoft’s outage adds a separate operational risk to cloud reliance. The news does not establish a broad credit deterioration, but scrutiny of Nvidia’s vendor-financing capacity makes funding conditions an important test for the AI supply chain.
October PPI came in cooler than expected at 0.3% month over month versus 0.4% forecast and 6.5% year over year versus 6.6% forecast, easing near-term pressure for Fed hikes. But core goods accelerated at their fastest pace since May, and annualized PPI reached a 47-month high, so inflation risks remain. Treasury yields edged lower in a bull steepening, the dollar strengthened amid risk aversion, and commodities fell even as energy and food costs remained elevated. The Nasdaq 100 dropped 2% and broke below its 200-day moving average, showing that the cooler headline inflation print could not offset the technology-specific shock.
Forward Catalysts
- Nvidia’s earnings on Tuesday: Investors will assess AI demand, China-related sales exposure and the potential impact of vendor financing.
- U.S. action on remote access to advanced AI chips: The timing is unspecified, but final rules could affect companies relying on overseas data centers to serve Chinese customers.
- Corteva’s delayed SEC filing and restructuring update: Management has deferred further restructuring clarity until February.
ACTIONABLE IDEAS
Actionable Ideas (Negative)
- NVDA(Nvidia): Fresh scrutiny of chip flows to China has widened the leadership shock into export-control and AI-growth concerns, alongside a sharp semiconductor selloff. Avoid adding to the dip ahead of Tuesday’s earnings; require evidence on order quality, China exposure and financing capacity before rebuilding positions.
- CTVA(Corteva): Brazil demand weakness and excess inventory drove a sharp guidance cut, while the delayed SEC filing adds disclosure risk. Underweight until the filing lands and management provides credible evidence of inventory normalization and a recovery in Brazilian demand.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 12, 2026
THOUGHT OF THE DAY
Nvidia leadership shock accelerates chip rotation
Jensen Huang’s sudden resignation pushed Nvidia’s existing espionage and export-control overhang into a leadership and governance crisis, prompting investors to reassess concentrated exposure to its AI ecosystem. The market recovered from early losses, but today’s shift toward rivals reflects a sharper repricing of Nvidia-specific risk—not evidence yet that hyperscalers have moved orders elsewhere.
Signal: Favor diversified AI-chip alternatives on a relative basis, while watching Nvidia’s next earnings report and any new export-control disclosures for proof that the rotation can persist.
Guidance cuts broaden the earnings deterioration
The concern spread beyond DraftKings’ previously reported reset: Corteva missed estimates and cut its 2026 outlook, while Cardinal Infrastructure withdrew full-year guidance after project cost revisions drove a severe margin collapse. The new signal is breadth—more companies are acknowledging weaker earnings visibility and execution risk.
Signal: Reduce exposure to companies with fragile margins, uncertain project controls, or guidance dependent on aggressive growth assumptions.
MACRO SUMMARY
Today’s corporate signals point to a split economy: AI infrastructure and selected industrial and defense businesses still report strong demand, but housing affordability, airline fuel costs, and weaker agricultural conditions weigh on other sectors. Existing home sales fell 5.5% month over month to 3.75 million, a 15-year low, while elevated mortgage rates continued to constrain activity. Airlines face a separate cost shock: Delta’s fuel expense rose 62% year over year to $4.2 billion in Q3. By contrast, the strong AI investment cycle continues to support demand for chips, networking, and power infrastructure, even as investors question the returns on that spending.
Inflation and tighter financial conditions remain the main macro constraint. Initial jobless claims were 200,000 versus 195,000 expected, and continuing claims were 1.697 million versus 1.710 million expected, signaling a still-resilient labor market. Hotter CPI, rising rates, a stronger dollar, and Federal Reserve Governor Waller’s mention of a possible 50-basis-point hike keep rate risk elevated; precious metals and other non-energy commodities sold off, while oil edged higher. Stocks rebounded broadly after early Nvidia-driven losses, with ten of eleven sectors advancing, but higher borrowing costs sharpen the risk for capital-intensive AI infrastructure and debt-dependent companies.
Forward Catalysts
- Wholesale inflation data (PPI) tomorrow: The release will test whether inflation pressure is easing or reinforcing expectations for tighter policy.
- Nvidia earnings next week: Investors will scrutinize demand, guidance, and management’s response to the leadership transition and export-control scrutiny.
- Cardinal Infrastructure’s data-center project update in March/April: Phase 2 timing and evidence of better project controls will test whether the company can stabilize margins.
ACTIONABLE IDEAS
Actionable Ideas (Positive)
- AMD(Advanced Micro Devices): Nvidia’s leadership shock is strengthening the relative case for established alternatives, while AMD’s full-stack products and hyperscaler relationships provide a foundation beyond the day’s rotation. Use AMD as a tactical relative-value position against Nvidia, sized for its premium valuation and the risk that no customer orders have shifted yet.
- AVGO(Broadcom): Investors are rotating toward diversified AI infrastructure exposure, and Broadcom’s custom accelerators and networking offer less dependence on the GPU market alone. Prefer it for diversified semiconductor exposure, but look for earnings confirmation before treating the rally as a durable fundamental re-rating.
Actionable Ideas (Negative)
- NVDA(Nvidia): Huang’s sudden resignation compounds existing governance, espionage, and export-control risks. Underweight the stock until the leadership transition stabilizes and earnings demonstrate that customer demand and the product roadmap remain intact.
- CTVA(Corteva): A steep Q3 miss, collapsing Latin American sales, and a lower full-year outlook point to deteriorating fundamentals rather than a routine forecast adjustment. Avoid buying the drawdown until management shows a credible recovery in regional demand and profitability.
- CDNL(Cardinal Infrastructure Group): Margin fell to 4.2% from 17.5% as project cost revisions forced the company to withdraw full-year guidance. Underweight pending evidence that estimating and project oversight have improved; backlog alone does not offset the loss of earnings visibility.
- DKNG(DraftKings): The 72% reduction in 2026 adjusted EBITDA guidance exposes the cost of its Predictions strategy, with substantial projected losses and regulatory risk ahead. Avoid adding exposure until the company demonstrates tighter spending and a clearer path to sustainable profitability.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 11, 2026
THOUGHT OF THE DAY
Contract-Backed Refinancing Eases AI Credit Stress
CoreWeave’s funding economics reset today: it moved from unsecured borrowing at 14–15% to customer-contract-collateralized loans at 7–7.5%, easing a key concern around financing its expansion and triggering a sharp rally across AI infrastructure stocks. The relief reflects stronger lender confidence in contracted cash flows, not an end to sector-wide leverage risk.
Signal: Favor infrastructure names with durable customer contracts; watch whether peers can secure comparable financing and whether credit spreads stabilize.
Atlassian Slashes Cloud Growth Outlook
Atlassian cut its Q2 cloud growth outlook to 27% from 30.5% and FY2027 subscription ARR growth to about 18.5% from 23%. The reductions prompted a roughly 16% share-price drop, showing that investors now demand evidence that AI investment can offset slowing core growth.
Signal: Underweight TEAM(Atlassian) until cloud and ARR growth stabilize; watch the next update for evidence of AI monetization and customer expansion.
MACRO SUMMARY
Today’s corporate signals point to a bifurcated economy: AI compute demand and financing remain strong where providers can show contracted revenue, while software growth expectations are weakening. CoreWeave’s $132.5 billion backlog and $9 billion in expected customer prepayments support expansion, but the financing relief is not broad-based: Applied Digital still faces leverage concerns after a rating downgrade, underscoring how sharply credit markets distinguish secured cash flows from debt-funded growth.
Demand outside AI also looks uneven. Atlassian’s lower cloud and subscription growth outlook, record-low small-business sentiment reported by Principal Financial, and Taylor Wimpey’s reduced homebuilding target amid weak affordability point to pressure in software and rate-sensitive parts of the economy. Cost and financing burdens remain visible too: mining costs rose 24% year over year at Agnico Eagle and 25% at Newmont, while Oracle’s recent bond issuance carried a 7.77% weighted-average coupon. The overall picture is strong investment demand in selected AI infrastructure, but continued scrutiny of growth quality, margins, and the cost of capital.
Forward Catalysts
- NVIDIA earnings and Anthropic’s IPO: Both are identified as tests of the durability of AI infrastructure demand and its circular financing model; timing was not specified.
- November 16 — AECOM earnings: Management guidance will indicate whether its federal and infrastructure pipeline can offset a softer sector backdrop.
- November 17 — Credicorp strategic update: Watch for clarity on growth priorities and capital allocation.
- November 18 — Expeditors Investor Day: Management’s outlook will test whether its strong earnings momentum supports its premium valuation.
ACTIONABLE IDEAS
Actionable Ideas (Positive)
- CRWV(CoreWeave): The shift from 14–15% unsecured borrowing to 7–7.5% customer-contract-collateralized loans materially reduces financing pressure. Favor the improved credit profile, but do not chase the sharp rally; watch refinancing execution and the conversion of backlog and prepayments into recurring cash flow.
Actionable Ideas (Negative)
- TEAM(Atlassian): The cuts to Q2 cloud growth and FY2027 subscription ARR growth show a clear deterioration in forward expectations. Underweight the stock and avoid buying the dip until management demonstrates that cloud growth has stabilized.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 10, 2026
THOUGHT OF THE DAY
Hot CPI Triggers Hawkish Fed Repricing
October headline CPI rose 0.4% month over month and core CPI 0.3%, both above forecasts, while Fed Governor Waller raised the possibility of a 50-basis-point December hike. The inflation surprise reinforced labor-driven hike concerns: markets now price a December increase as certain, with an 11% chance of a 50-basis-point move, and the two-year Treasury yield jumped 18 basis points.
Signal: Reduce exposure to rate-sensitive, long-duration assets until inflation data or Fed communication challenges the higher-for-longer repricing.
Hims Cuts Guidance as Margins Collapse
HIMS(Hims & Hers Health) cut its 2026 revenue and EBITDA outlook as gross margin fell 17 percentage points, from 74% to 57%, and subscribers declined sequentially by 100,000. The combination breaks the growth-at-all-costs narrative: rising revenue no longer offsets deteriorating unit economics and weaker subscriber momentum.
Signal: Avoid the stock until management demonstrates margin stabilization and a return to sequential subscriber growth.
MACRO SUMMARY
Today’s Read: The macro signal turned decisively more hawkish. October CPI exceeded forecasts across headline and core measures, with price increases broadening across gasoline, electricity, transportation services, and food. ADP’s weekly payroll average also accelerated to 19,750 from 16,750, adding evidence of labor-market resilience. The two-year Treasury yield rose 18 basis points, the dollar strengthened, and markets priced a December rate hike as certain, including an 11% probability of a 50-basis-point move. Falling WTI—down to $83.88 per barrel—offers some relief on energy costs, but it did not offset the inflation surprise.
Corporate results point to uneven demand and persistent margin pressure, not a broad-based collapse. Travel and logistics companies reported strong activity, while home improvement and construction signals remained softer: Home Depot’s comparable sales gains came alongside lower transaction counts, and Amrize reported declining cement volumes and margin contraction. Cost pressure remains visible in fuel, freight, and input expenses, while Hims’ sharp margin decline shows that company-specific execution can compound the macro strain. Higher yields also raise the hurdle for debt-funded investment, making capital-intensive businesses more vulnerable if demand or financing conditions weaken.
Forward Catalysts
- November 25 PCE inflation data and the next readings on November inflation: evidence of cooling—or renewed persistence—will shape the rate outlook.
- The December Fed decision: Waller’s 50-basis-point warning raises the stakes for the policy meeting; watch for confirmation or retreat from the hawkish repricing.
- December 10 CPI report: A further inflation surprise could reinforce higher-for-longer expectations; a decline, particularly if oil stays in the $80s, could ease pressure.
ACTIONABLE IDEAS
Actionable Ideas (Positive)
- CME(CME Group): October activity showed a 48% increase in U.S. Treasury futures and options volume, including a 58% rise in 10-year Note average daily volume. Position for continued earnings leverage if rate volatility and hedging demand persist.
Actionable Ideas (Negative)
- HIMS(Hims & Hers Health): The company cut its 2026 outlook as gross margin fell to 57% and subscribers declined sequentially. Avoid or underweight until the company proves it can stabilize margins and restore subscriber growth.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 9, 2026
THOUGHT OF THE DAY
Nvidia Espionage Scandal Raises Security Risk
Confirmation that Nvidia’s CEO was a target of a foreign intelligence effort pushed NVDA(Nvidia) down 8% even as equities rallied broadly. The divergence puts fresh focus on export-control exposure and governance risk at the center of the AI supply chain; it does not, by itself, establish that Nvidia knowingly diverted restricted chips.
Signal: Trim or hedge concentrated NVDA(Nvidia) exposure until investigations clarify the company’s governance and export-control risks; watch for evidence that customers shift toward alternatives such as AMD(Advanced Micro Devices).
DraftKings Quantifies Prediction-Market Risk
DKNG(DraftKings) added a sharper measure of downside to its already-covered EBITDA reset: management warned that prediction markets could lose as much as $1 billion through 2027. That figure puts a concrete cost on the Predictions strategy as the company cuts 2026 adjusted EBITDA guidance to $175–275 million from $700–900 million and the stock falls 21%.
Signal: Keep a cautious or underweight stance on DKNG(DraftKings); track prediction-market spending and evidence of customer payback against the growing loss burden.
MACRO SUMMARY
Today’s Read: Companies signal a split economy: investment in AI infrastructure remains strong, but its returns and financing are under greater scrutiny. Hyperscaler demand and supplier backlogs support continued spending, while Apple and Amazon are imposing controls on AI usage costs and lenders are reassessing long-dated data-center exposure. The corporate message is capex is still expanding, but investors increasingly demand proof that it can convert into durable cash flow.
Demand remains uneven. Digital sales growth at retailers such as BJ’s and Costco points to continued traction in convenient, value-oriented channels, while housing-linked and rate-sensitive businesses face pressure. Lower crude prices offer cost relief and ease fuel-driven inflation concerns. But the rates backdrop remains restrictive: futures put the probability of a December Fed hike at 85%, short-term Treasury yields rose ahead of CPI, and longer yields were little changed. The dollar weakened as oil fell to a 10-week low, while the broad equity rally—S&P 500 up 1.8%, Nasdaq 100 up 3.3%, all sectors higher—showed investors willing to look through company-specific risks for now.
Inflation signals remain mixed. The market needs October CPI at 0.2% month over month or lower to sustain the rally, while stronger growth expectations and China’s 5.7% producer-price inflation complicate the disinflation story despite Chinese CPI at just 0.7% year over year. Lower fuel costs help the near-term inflation outlook, but elevated producer prices and the high probability of a Fed hike leave little room for a hot CPI surprise.
Forward Catalysts
- Tuesday: October U.S. CPI, the last inflation reading before the Fed’s final 2026 decision.
- Final 2026 Fed decision: Watch for confirmation of the market’s rate expectations and implications for yields and risk assets.
- November 17: NVDA(Nvidia) earnings, with results and management commentary likely to face added scrutiny around governance, export controls, and AI demand.
ACTIONABLE IDEAS
Actionable Ideas (Positive)
- AMD(Advanced Micro Devices): Google Cloud selected AMD’s fifth-generation EPYC processors as the host layer for its TPU 8tx system, adding a significant hyperscaler integration to AMD’s already strong data-center growth. Use the Nvidia governance shock to build diversified AI-chip exposure through AMD, while monitoring whether the win leads to broader adoption.
Actionable Ideas (Negative)
- DKNG(DraftKings): The cut to 2026 adjusted EBITDA guidance and warning of up to $1 billion in prediction-market losses through 2027 make the Predictions investment a material earnings and capital-allocation risk. Underweight the shares and require evidence of a credible path to customer payback before adding exposure.
- NVDA(Nvidia): The CEO’s confirmation as a target of a foreign intelligence effort adds governance and export-control risk, and the stock fell 8% against a broad market rally. Reduce or hedge concentrated positions pending clearer findings from the investigations and a fuller assessment of customer and regulatory fallout.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 8, 2026
THOUGHT OF THE DAY
Persian Gulf LNG Disruptions Tighten Global Supply
Today’s flow reverses the recent easing narrative: Iran-related disruption is now contributing to an estimated 20 Bcm LNG shortfall, while Europe heads toward its lowest storage levels since 2013. The combination raises the risk of an aggressive summer refill cycle and tighter competition for cargoes ahead of winter.
Signal: Favor tactical exposure to a tighter gas balance through UNG(United States Natural Gas Fund), but size for sharp volatility and potential demand-side offsets.
Moderna’s Profitability Rebound Resets the Post-Pandemic Story
MRNA(Moderna) moved from a $200 million year-ago loss to a $162 million quarterly profit, cut its 2026 capex forecast to $200 million, and raised its full-year revenue-growth outlook to 15%–25%. That combination of lower spending and stronger guidance marks a clear improvement in the post-pandemic trajectory, rather than a revenue beat alone.
Signal: The turnaround thesis has gained credibility; watch whether cost discipline and revenue growth persist beyond current vaccine demand.
MACRO SUMMARY
Today’s corporate signals point to uneven demand, not a broad-based slowdown. AI infrastructure spending remains strong, with cloud, networking, and power-related commitments supporting demand across the supply chain. But conversion into durable profits remains uncertain: CRWV(CoreWeave) faces an $85 billion funding need against its backlog, while AMZN(Amazon) and MSFT(Microsoft) are committing heavily to infrastructure. Consumer signals are mixed: TAP(Molson Coors Beverage) cut its outlook as volumes and margins weakened, while other companies reported resilient demand or growth in healthcare and essential services.
Cost and financing pressure remain central risks. The LNG disruption threatens a fresh energy-cost shock, while companies also cite raw-material, memory, labor, fuel, and logistics expenses as constraints on margins. Results across sectors show that revenue growth does not consistently translate into earnings: CF(CF Industries) missed EPS despite beating revenue, and CSCO(Cisco Systems) reported lower gross margins amid hardware mix and memory costs. Funding access also separates winners from vulnerable businesses: BEPC(Brookfield Renewable Corporation) reported substantial financing capacity, while CoreWeave’s capital requirement highlights the exposure of highly leveraged AI expansion.
Forward Catalysts
- Upcoming earnings: AMAT(Applied Materials), CSCO(Cisco Systems), and CEG(Constellation Energy) reports could clarify semiconductor capex, AI-network demand, and nuclear-power economics.
- November 9: HIVE(HIVE Digital Technologies) reports Q3 results; investors will focus on power costs, efficiency, and data-center execution.
- Policy and regulatory decisions: The U.S. defense-budget debate during the lame-duck session could affect major programs at LMT(Lockheed Martin) and NOC(Northrop Grumman). State rate cases for PPL(PPL Corporation), along with regulatory approvals for the AWK(American Water Works)–Essential Utilities merger, remain key utility-sector watchpoints.
- LNG balance: Europe’s summer storage refill ahead of the 2026–27 heating season will test the market’s ability to secure replacement cargoes amid Persian Gulf disruption.
ACTIONABLE IDEAS
Actionable Ideas (Positive)
- ** UNG(United States Natural Gas Fund):** Persian Gulf disruption has reversed the easing supply narrative and widened the projected global LNG shortfall to 20 Bcm as European storage approaches a multi-year low. A tactical long position can capture further supply-driven price spikes, with strict risk limits given the fund’s futures exposure and gas-market volatility.
- ** MRNA(Moderna):** Quarterly profitability, a sharp capex reduction, and raised full-year revenue-growth guidance improve the quality of the turnaround case. The actionable angle is to favor the improving earnings and cash-discipline story, while monitoring whether revenue growth holds as demand normalizes.
Actionable Ideas (Negative)
- ** TAP(Molson Coors Beverage):** Management now expects 2026 net sales to fall 1%–2% and underlying EPS to decline 16%–19%, while global beer-brand volumes fell 4.9%. The guidance reset and market-share losses support a bearish stance until volumes and margins stabilize.
- ** CHTR(Charter Communications):** A $6.3 billion franchise impairment and a $2.397 billion quarterly loss expose the weakness of the cable business and raise execution risk around the planned cost reset. Avoid the turnaround until subscriber trends improve and promised savings become visible in results.
- ** CRWV(CoreWeave):** The $85 billion financing requirement to support a $104.2 billion backlog, combined with customer concentration, makes execution dependent on continued access to capital. The risk-reward remains skewed down until management provides credible funding and margin visibility.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.
Daily Market Pulse November 7, 2026
THOUGHT OF THE DAY
Oil risk premium collapses on U.S.–Iran thaw
Crude fell roughly 12% in a week, its steepest weekly decline since early 2020, as diplomatic de-escalation with Iran met recovering Middle Eastern supply. The move marks an acceleration of the decline already underway: improved supply now reinforces the unwind of geopolitical risk premium. Natural gas did not move in lockstep; cooler weather supported a modest weekly gain in gas futures.
Signal: Favor a bearish crude stance through USO.US(United States Oil Fund), but treat UNG.US(United States Natural Gas Fund) as a separate weather-and-gas-market trade.
Pelacarsen failure rattles the Lp(a) drug thesis
Novartis halted pelacarsen after its Phase 3 trial failed to reduce cardiovascular events despite lowering Lp(a). That result challenges the assumption that lowering the biomarker will translate into fewer heart attacks and strokes, putting competing programs—including Amgen’s olpasiran—and related royalty exposure under scrutiny.
Signal: Reassess Lp(a)-linked pipeline and royalty valuations; the next critical test is whether olpasiran can show cardiovascular benefit, not just biomarker reduction.
MACRO SUMMARY
Today's Read: Corporate news points to strong but uneven growth. AI infrastructure demand remains tangible: AMD(Advanced Micro Devices) reported 97% growth in data-center revenue and guided to roughly $17 billion in Q4 revenue, while AAOI(Applied Optoelectronics) secured a hyperscaler agreement for 1.6T transceivers worth an estimated $1–1.5 billion through 2029. Yet demand does not guarantee attractive returns. CoreWeave’s debt burden, bond yields above 17%, and exposure to permitting delays show how financing costs and political constraints can disrupt the buildout.
Consumer signals also diverge by category. ABNB(Airbnb) and BKNG(Booking Holdings) reported strong travel demand and pricing, while weakness at Wynn and pressure on IFF’s supplement-related sales point to softness in parts of discretionary spending. Cost pressure remains visible: IFF expects an unfavorable price-cost gap into Q4, and labor, energy, and logistics costs continue to weigh on several companies. The oil selloff could ease some energy-cost pressure, but today’s corporate reports do not yet show broad relief.
Forward Catalysts
- CEG(Constellation Energy), NRG(NRG Energy), and OXY(Occidental Petroleum) report earnings next week, according to the summaries.
- NVDA(NVIDIA) reports Q3 earnings on November 17; investors will watch for signs that AI demand and margins can sustain current expectations.
- BEP(Brookfield Renewable Partners) faces a November 25 deadline for the vote on its BEPC simplification proposal.
ACTIONABLE IDEAS
Actionable Ideas (Positive)
- AMD(Advanced Micro Devices): Data-center revenue rose 97% year over year to $8.55 billion, and management guided to approximately $17 billion in Q4 revenue. The results support exposure to AI compute demand, while supply constraints remain the key execution risk.
- AAOI(Applied Optoelectronics): A Tier 1 hyperscaler signed a multi-year 1.6T transceiver agreement projected to generate $1–1.5 billion through 2029. The contract materially improves demand visibility; position for execution only with the capacity and DSP bottlenecks in view.
Actionable Ideas (Negative)
- USO.US(United States Oil Fund): Crude’s roughly 12% weekly decline reflects both easing U.S.–Iran tensions and recovering supply. Maintain bearish crude exposure while the geopolitical premium continues to unwind; watch for renewed supply disruption or a reversal in diplomacy.
- IONS(Ionis Pharmaceuticals): Novartis discontinued pelacarsen after the Phase 3 trial failed to reduce cardiovascular events, undermining confidence in the Lp(a) approach. Reduce exposure until competing clinical evidence supports a clear link between Lp(a) lowering and fewer cardiovascular events.
- RPRX(Royalty Pharma): Its royalty interest in Amgen’s olpasiran now faces heightened risk after the pelacarsen failure triggered a class-wide reassessment. Discount the royalty asset until olpasiran demonstrates clinical-outcome benefit.
- CRWV(CoreWeave): Debt above $51 billion, bond yields above 17%, and permitting risks expose the company to acute refinancing and project-delivery pressure. Avoid or underweight until funding access and capacity execution stabilize.
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Always consult a qualified financial professional before making any investment decisions.